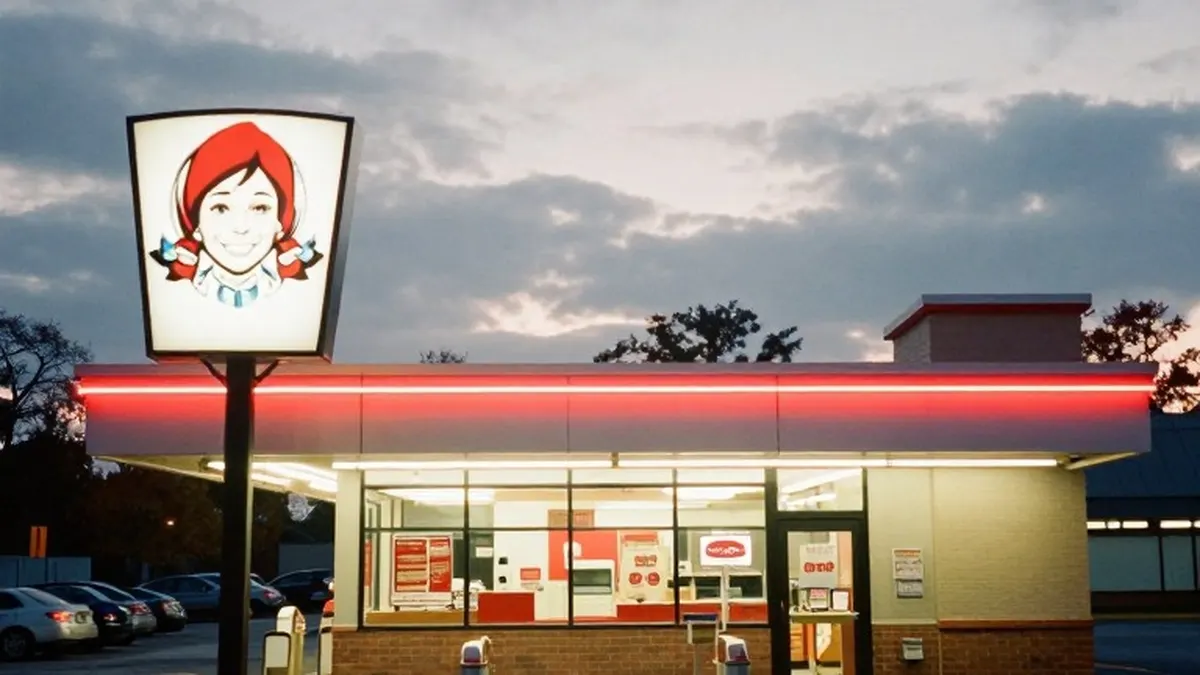
Shares of Wendy's climbed about 15% in morning trading on Wednesday after a group of investors led by Nelson Peltz's Trian Fund Management proposed buying the burger chain for $1.4 billion, according to a regulatory filing.
The group is offering $7.35 per share in cash to take the company private. That price represents a 20% premium over Tuesday's closing share price. Joining Trian in the bid are the investment firms BlueFive Capital and Sixth Street Partners, along with Flynn Group, one of Wendy's largest franchisees. The Wall Street Journal was the first to report on the proposal.
Wendy's did not immediately respond to a request for comment from CNBC, and Trian declined to comment beyond what appears in the filing. Trian and affiliated parties hold a 16.25% stake in Wendy's, which makes them the company's largest shareholder, the filing shows.
The offer arrives after a punishing stretch for the fast-food company. Even with Wednesday's jump included, Wendy's stock has fallen 65% over the past two years. The chain has also posted declines in same-store sales for six consecutive quarters. It is scheduled to release third-quarter earnings before the market opens on Nov. 5.
That slump has made Wendy's a cheaper target for Peltz, whose history with the brand goes back more than two decades to an activist campaign he led. Trian also looked into a takeover of the company in 2022 but ultimately decided against pursuing it.
Industry conditions have not helped. Budget-conscious customers are dining out less often, and Wendy's and its competitors have relied on discounts to bring people back into restaurants. Wendy's has also cycled through a number of chief executives, each with a different view of how to turn the business around.
The latest is Bob Wright, the former CEO of Potbelly, who joined Wendy's in May after his previous employer went private. On his first earnings call with analysts in August, Wright spoke candidly about what he sees as the chain's main problems: unclear value offerings, inconsistent execution in restaurants and too many one-off promotions.
TD Cowen analyst Andrew Charles told clients in a note on Wednesday that a buyout makes sense. "In our view, a take private makes sense as Wendy's turnaround is likely to be prolonged given the challenged state of the lower income consumer and soft state of the quick service burger category," he wrote.